PPO Network Access for High Earners: What You Give Up (and Gain) Moving From ACA to a Private Plan
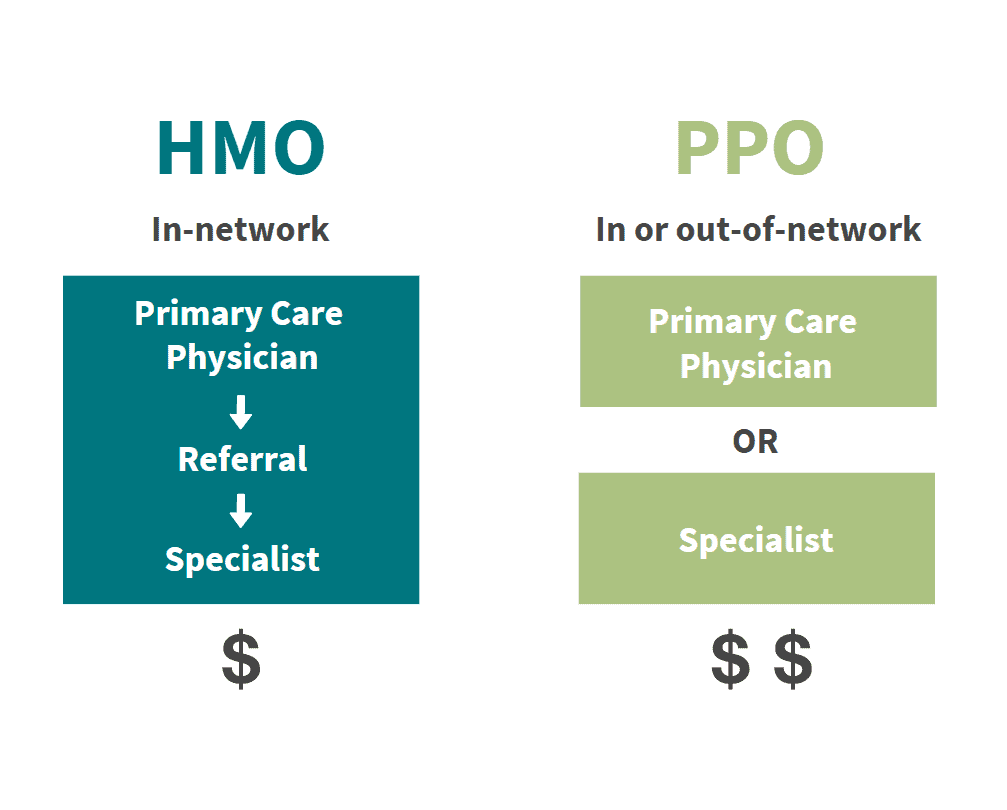
Quick answer: Many ACA marketplace plans use narrower HMO or EPO networks with referral requirements and little or no out-of-network coverage. Private plans from major carriers frequently offer broader PPO networks with out-of-network benefits and no referrals. The trade-off is that private plans are medically underwritten, so coverage isn’t guaranteed, and they aren’t HSA-eligible. If […]
How High-Income Business Owners Should Structure Household Health Coverage in 2026
Quick answer: Most business owners keep the family health plan they picked when the business was smaller. Once household income passes the ACA subsidy line ($128,600 for a family of four in 2026), that plan is priced at full unsubsidized rates, and it’s rarely revisited. The three structures worth comparing each year are a single […]
Why the ACA Subsidy Cliff Hits High-Income Households Hardest in 2026
Quick answer: For 2026 coverage, ACA premium tax credits end completely at 400% of the federal poverty level: $62,600 for a single person, $84,600 for a two-person household, and $128,600 for a family of four. Earn one dollar over the line and the credit drops to zero. Households just above the cutoff pay the full […]
High Income Earner? Why You’re Probably Overpaying for Health Insurance!
Quick answer: If your household income is above the ACA subsidy threshold (about $62,600 for a single filer in 2026), you get no premium assistance and pay full price on the marketplace. Medically underwritten private health plans can cost less than full-price ACA plans for healthy applicants in this income bracket, which is why many […]